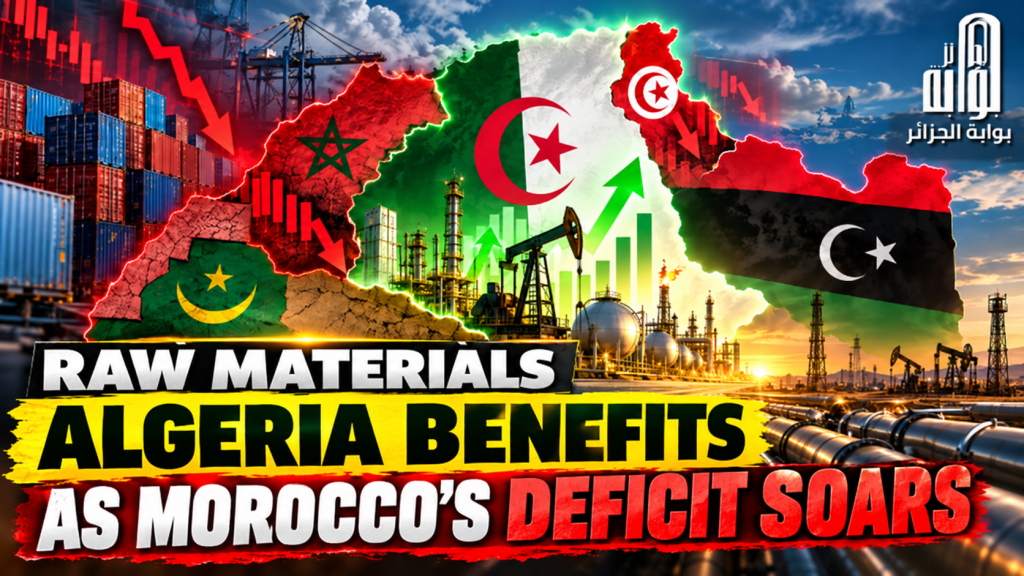
Algeria Gate: The rise in energy and cereal prices does not hit Maghreb economies in the same way. Algeria, an exporter of oil and gas, benefits directly from the increase in hydrocarbons. Morocco, despite its phosphates and fertilisers sector, sees its trade deficit widen sharply. Tunisia, for its part, remains heavily penalised by its energy dependence.
World Bank data illustrate this new tension on raw materials. In its Pink Sheet published in September, the institution indicated notably that its energy index had risen by 8.8% in August, with a 10.1% increase in natural gas. Brent had moved from $83.4 a barrel in July to $90.9 in August. Cereals were also trending upward: maize rose from $213.4 to $224 a tonne and US HRW wheat from $310 to $330.
The World Bank also noted at the end of September that between June and mid-September 2026, world cereal prices had increased by 18%, wheat by 22% and maize by 26%.
Algeria: the rise in hydrocarbons works in favour of revenues
For Algeria, this situation brings an immediate advantage: the rise in oil and gas prices increases the value of energy exports and public revenues.
The IMF estimates that the rise in hydrocarbon prices should stimulate Algerian exports and budget revenues in 2026, while helping to reduce the external deficit. The institution also forecasts growth of 3.8% this year.
This upturn does not mean that the Algerian economy is immune to all risks: the IMF also highlights the high level of the budget deficit and the recent erosion of reserves. But in the short term, the rebound in hydrocarbons offers Algiers an additional source of foreign currency and revenue.
The rise in cereals, on the other hand, constitutes a cost for Algeria, which remains an importer of wheat and other food products. The shock is therefore double, but the importance of hydrocarbon exports gives the country a buffer that its neighbours do not have to the same degree.
Morocco: phosphates are not enough to prevent the trade deficit from widening
Morocco does have a significant phosphates and fertilisers industry. But official figures show that this asset does not prevent a significant deterioration in its trade balance.
Over the first eight months of 2026, Moroccan imports jumped by 15.8% to 617.5 billion dirhams. Exports rose by only 8.7% to 334.9 billion. As a result, the trade deficit increased by 25.4%, reaching around 282.6 billion dirhams, while the coverage rate lost 3.5 points.
Phosphates themselves were not systematically spared. Over the first four months of 2026, Moroccan exports of phosphates and derivatives had fallen by 1.5%. Sales of natural and chemical fertilisers had declined by 3.9%, while exports of raw phosphates fell by 3.2%.
In other words, presenting fertilisers as a sufficient shield against the energy shock would be excessive. They constitute an important source of foreign currency, but the external trade figures show that they do not offset the much faster rise in imports.
The contrast with Algeria is therefore notable: when energy becomes more expensive, Algiers can increase its export revenues, whereas Rabat has to absorb a heavier import bill in an already strongly deficit trade balance.
Tunisia: nearly 9 billion dinars of energy deficit
Tunisia appears even more exposed. During the first eight months of 2026, its overall trade deficit reached 17.85 billion dinars, compared with 14.64 billion a year earlier.
The energy deficit alone amounted to 8.93 billion dinars, compared with 7.15 billion over the same period of 2025. It thus represents roughly half of Tunisia’s trade deficit.
Any further lasting rise in oil or gas prices therefore risks directly increasing pressure on the country’s foreign currency needs and external accounts.
A global shock, three very different situations
The rebound in raw materials ultimately acts as a revealer of Maghreb economic structures.
Algeria benefits from the rise in hydrocarbons thanks to its status as a major energy exporter. Morocco retains the phosphates asset, but it is not enough to prevent its trade deficit from rising by more than 25%. As for Tunisia, its dependence on energy imports continues to weigh heavily on its external accounts.
In a period of high prices, the balance of power is therefore very different: what produces additional revenues for Algeria becomes a heavier bill for its energy-importing neighbours.